Helmledgers Insights · Contract Liabilities
Why contract liabilities deserve a second look
Contract liabilities rarely get headline attention, but they often deserve far more scrutiny than they receive.
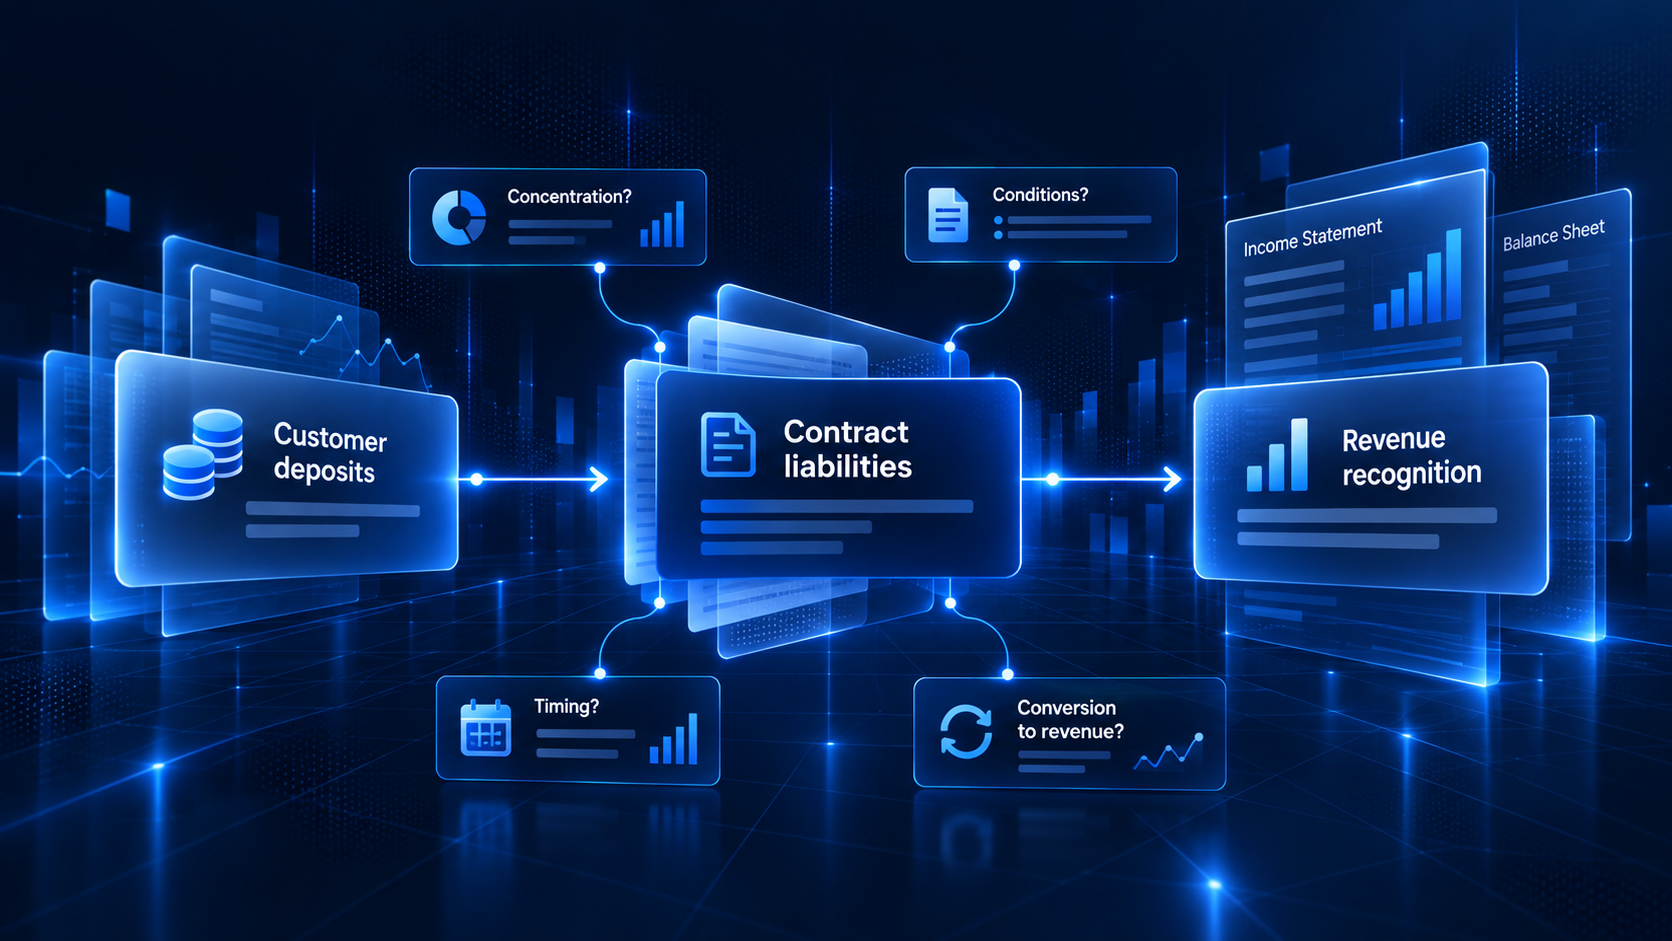
In simple terms, a contract liability reflects consideration received before the related goods or services are delivered. In many businesses that is entirely normal. But when balances move sharply, become unusually concentrated, or sit in noncurrent buckets for long periods, they can point to a more important underlying story.
For analysts, lenders and research teams, contract liabilities are not just an accounting line. They can be an early clue about customer behaviour, delivery commitments, funding reliance and the timing of future revenue recognition.
Why this line matters
A large or fast-growing contract-liability balance can raise useful questions such as:
- Are customers effectively pre-funding the business?
- How concentrated are those balances across counterparties?
- What delivery, refund or performance conditions sit behind them?
- How much future production or service capacity is already committed?
- Over what period will the balance unwind into revenue?
Those questions matter because the accounting balance is often only the surface layer. The real signal sits behind the disclosure.
What standard review often misses
A conventional review may note that contract liabilities increased and move on.
A better review asks what changed economically.
For example, a rising balance may reflect strong customer demand and improved visibility. But it may also reflect unusual deal structures, customer dependence, constrained supply, prepayment obligations, or revenue that will only be recognised over a much longer horizon than the headline story suggests.
This is why contract-liability analysis works best when it is tied back to the filing text, supporting disclosures and sector-specific context — not just the face value of the number.
A practical example: Micron
Micron offers a useful example of why this matters.
In its FY26 filings, Micron disclosed a major increase in customer contract-liability deposits. The company received $12.7 billion of customer deposits during FY26, leaving $12.9 billion of noncurrent contract liabilities at year-end, versus just $568 million at Q3.
That number is striking in itself. But the more important analytical questions sit behind it:
- Who are the counterparties?
- How concentrated are those deposits?
- What refund or performance conditions apply?
- How much future supply is effectively committed?
- When do those balances convert into revenue?
Those are the questions that shape interpretation. Without them, the balance may be noted, but not properly understood.
Source: Micron FY26 Form 10-K ↗
What analysts should look for
When reviewing contract liabilities in SEC filings, it helps to work through a simple sequence:
- 1Size and changeHas the balance moved materially versus the prior quarter or year? Is the movement operationally intuitive, or does it stand out?
- 2Current vs noncurrent splitA noncurrent build can be especially important, because it suggests a longer-dated obligation or delivery profile.
- 3Filing contextDoes management explain the driver clearly, or is the disclosure thin?
- 4Link to revenue recognitionHow and when will the balance unwind into reported revenue?
- 5Counterparty and concentration riskIf the balance is economically significant, concentration may matter as much as the total amount.
The broader point
Contract liabilities do not automatically signal a problem. In many cases they reflect healthy demand, strong order books or normal commercial practice.
The key point is that they should not be treated as a routine line item by default.
When reviewed properly, contract liabilities can help surface questions about commercial structure, customer reliance, delivery obligations and future revenue timing — exactly the kinds of issues that are easy to miss in a standard pass through a filing.
Final takeaway
If a balance-sheet line is large, changing quickly, or sitting in a place the market is not discussing, it is usually worth asking a second question.
Contract liabilities are one of those lines.
They are not just deferred revenue mechanics. In the right context, they can be an early signal about what the business has promised, what it still needs to deliver, and what the market may not yet be fully pricing in.
Illustrative analysis only. Not investment advice.