Credit Risk · Forensic Accounting ·
Supplier Finance, Hidden Leverage and the Risks Behind Reported Cash Flow
Why institutional credit investors should examine reverse factoring, structured payables and working-capital financing before accepting reported leverage and cash conversion at face value.
When trade payables become a financing question
Trade payables are an ordinary feature of corporate operations.
Businesses purchase goods and services, receive invoices and settle their obligations according to commercial terms.
However, certain supplier finance arrangements introduce a third-party financial intermediary into that process.
A supplier may receive payment from a bank or other finance provider before the buyer's contractual payment date. The buyer subsequently settles its obligation under the arrangement.
These structures can provide meaningful benefits. Suppliers may receive cash sooner, buyers may improve payment predictability and financing providers may earn a return for assuming exposure.
The analytical challenge arises when the arrangement changes the economic characteristics of working-capital funding.
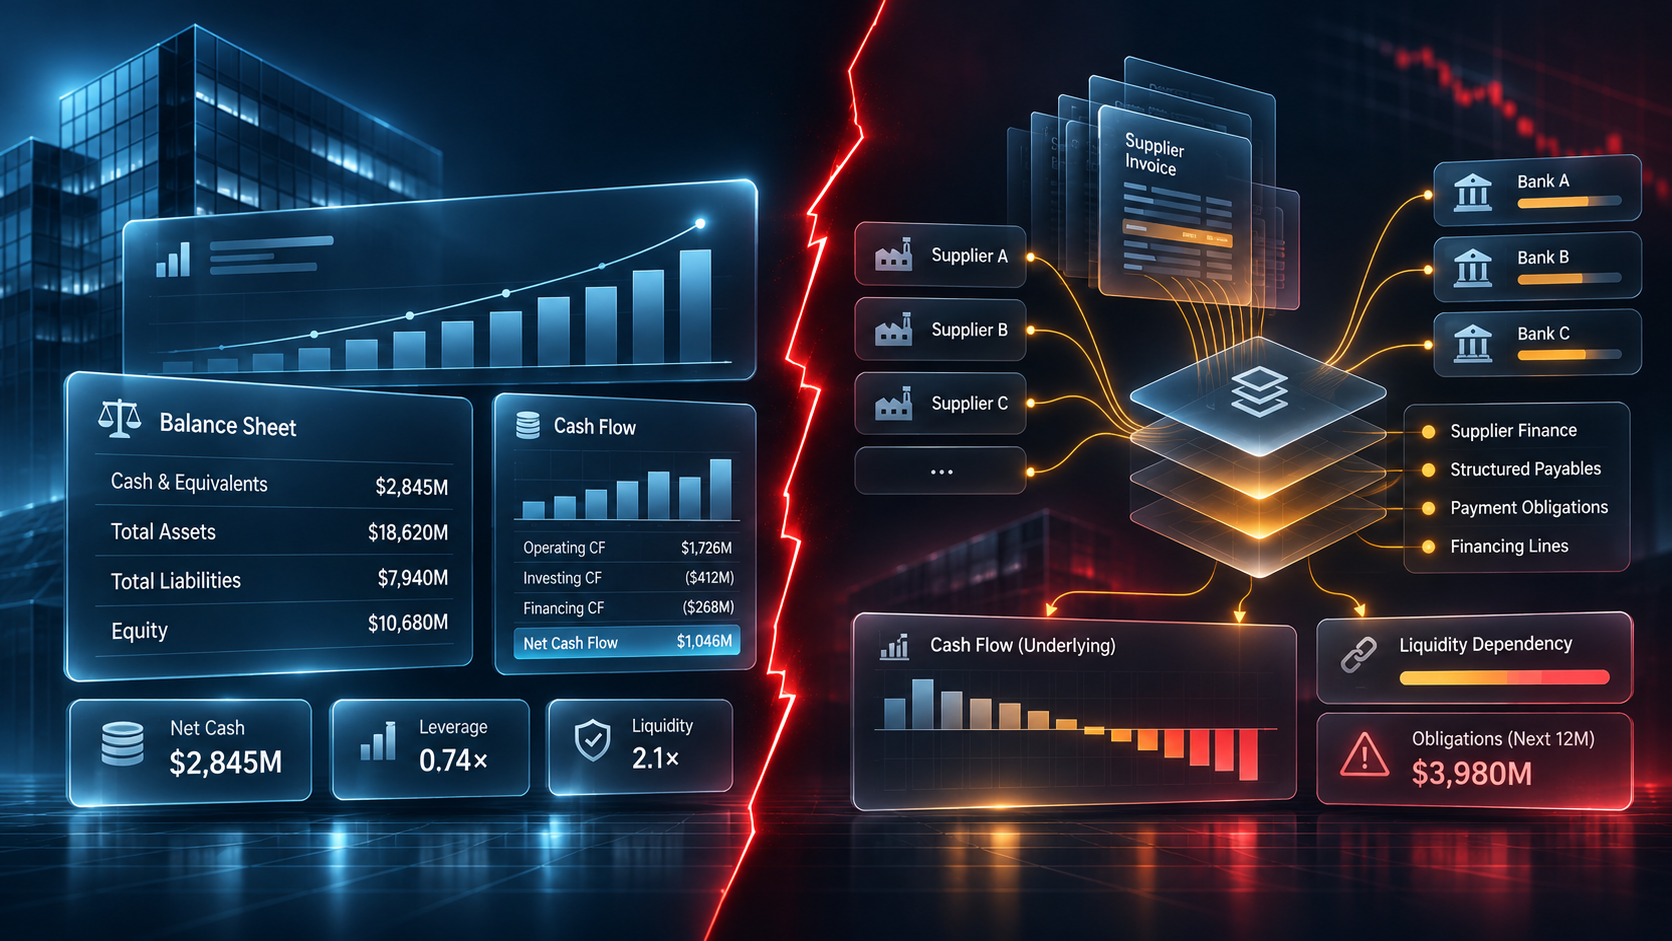
For institutional credit investors, a central question is whether reported trade payables and operating cash flow adequately communicate the company's financing dependence and liquidity exposure.
This is not an argument that all supplier finance programmes constitute hidden debt.
It is an argument that their economic implications should be investigated.
The most important risk may not be the financing arrangement itself, but what happens if the arrangement is no longer available on the same terms.
How reverse factoring differs from conventional payables
In a conventional trade payable relationship, a buyer owes a supplier for goods or services delivered.
In a supplier finance arrangement, the supplier may have the option to receive accelerated payment from a financing provider based on invoices approved by the buyer.
The buyer's legal and economic obligations depend on the structure and contractual terms.
Importantly, payment by a financing intermediary does not automatically mean that the buyer's liability must be classified as borrowings.
The accounting presentation depends on the applicable standards and the substance of the arrangement.
Nevertheless, these programmes can affect the way analysts interpret working capital, payment terms and potential liquidity requirements.
An apparently attractive cash conversion cycle may partly reflect financing arrangements rather than purely operating efficiency.
That distinction matters when comparing companies or assessing a business under financial stress.
Why conventional leverage ratios may be incomplete
Consider a hypothetical industrial business with the following balance sheet information:
| Financial item | Amount |
|---|---|
| Reported borrowings | $1.8 billion |
| Cash and equivalents | $400 million |
| Reported net debt | $1.4 billion |
| Supplier finance obligations included in payables | $600 million |
The company reports $1.4 billion of net debt using conventional borrowings less cash.
An analyst might separately consider the $600 million supplier finance exposure when assessing financing dependence.
If the analyst treated the entire amount as debt-like for a particular sensitivity case, the adjusted exposure would become $2.0 billion net of cash.
That is an analytical adjustment, not necessarily the correct accounting classification.
The appropriate amount depends on the terms, payment extension, liquidity characteristics and whether the obligations are already incorporated elsewhere in the analysis.
Avoiding double counting is essential.
The objective is to understand how the programme affects the company's capacity to meet obligations, particularly if the arrangement were reduced or withdrawn.
The importance of supplier finance disclosures
US GAAP now includes dedicated supplier finance disclosure requirements under ASC 405-50, introduced through FASB Accounting Standards Update 2022-04.
These disclosures cover information such as programme terms, outstanding confirmed obligations and their financial statement presentation.
Annual disclosures also include a rollforward showing amounts confirmed and subsequently paid.
The requirements improve transparency but do not themselves change the recognition, measurement or presentation of supplier finance obligations.
Internationally, amendments to IAS 7 and IFRS 7 similarly require enhanced information about supplier finance arrangements, their effects on liabilities and cash flows, and exposure to liquidity risk.
These standards create additional analytical opportunities for investment professionals.
They also make it possible to examine the evolution of supplier financing across reporting periods more systematically.
Four signals credit investors should monitor
1. Supplier finance growth relative to operating activity
The first question is whether the programme is expanding faster than the business.
A rising supplier finance balance may reflect increasing purchase volumes, broader supplier participation, extended payment terms or changes in working-capital management.
It should not automatically be interpreted as deteriorating credit quality.
However, an increase that materially exceeds relevant operating growth warrants explanation.
The analyst should compare outstanding programme obligations with revenue, purchases where available, cost of goods sold, trade payables and underlying cash flow performance.
Where annual rollforward information is available, it can provide additional insight into programme activity.
2. Changes in payment terms
Payment terms are central to understanding financing dependence.
If a buyer extends settlement periods while suppliers continue to receive earlier payment through a financing provider, the company's apparent working-capital position may improve.
That improvement could be economically sustainable.
Alternatively, it may increase dependence on the continued availability of the financing arrangement.
Credit analysis should distinguish a durable commercial improvement from a funding mechanism that could change during periods of financial stress.
3. Classification and cash flow effects
A further question concerns where programme obligations appear on the balance sheet and how related cash flows are classified.
Accounting treatment is fact-specific.
For example, a liability that retains the characteristics of a trade payable may be treated differently from an obligation that has substantively become borrowing.
The distinction can affect measures such as operating cash flow, financing cash flow, working capital and adjusted leverage.
Analysts should avoid assuming that every supplier finance payment belongs in financing activities.
Instead, they should analyse the contract, accounting policy and reported presentation before deciding whether a supplementary cash flow measure is appropriate.
4. Liquidity under programme withdrawal
Supplier finance arrangements may provide useful liquidity flexibility.
They can also introduce exposure to changes in financing-provider appetite, contractual terms or programme availability.
In credit analysis, this creates a stress-testing question.
What happens to the company's cash requirements if financing capacity contracts or the buyer must settle obligations on shorter terms?
The answer depends on the programme structure, supplier behaviour, available cash, credit facilities and alternative working-capital funding.
It cannot be derived from the programme balance alone.
A practical liquidity sensitivity example
Assume a company has $500 million of supplier finance obligations outstanding.
Suppose that, under a hypothetical stress scenario, $200 million of incremental cash settlement is required over the next quarter because the arrangement contracts and payment terms shorten.
If the company had expected $150 million of available liquidity after planned obligations, the additional settlement requirement would produce a $50 million funding gap unless other resources or operating changes offset it.
This is a simplified stress scenario, not a prediction.
In practice, the analyst would model maturity dates, contractual commitments, provider actions, replacement financing, supplier responses and the effect of any prior payment-term extension.
The important insight is that a company's reported debt balance may not fully describe the timing of its potential cash requirements.
For distressed or special-situations investors, that distinction can be critical.
Why annual rollforwards are valuable
A point-in-time programme balance provides only part of the picture.
The rollforward can help analysts understand the flow of obligations through the programme.
Relevant questions include:
- How much new activity entered the arrangement?
- How much was subsequently settled?
- Did the closing balance increase because of greater activity or slower payment?
- Are programme balances concentrated around reporting dates?
- Do the disclosed movements reconcile with the broader working-capital narrative?
Year-end balances should be interpreted alongside interim disclosures and changes in the company's operating activity.
A seemingly stable closing balance does not necessarily imply unchanged financing dependence throughout the year.
Equally, a large annual movement may reflect substantial transaction volume rather than increasing risk.
Cross-company comparisons require care
Supplier finance programmes differ materially between companies.
One business may provide suppliers with access to optional invoice discounting while retaining ordinary commercial payment terms.
Another may use a financing structure that meaningfully alters payment timing or liquidity exposure.
Comparing reported programme balances without examining contract terms can therefore create false equivalence.
For institutional investors, useful cross-company analysis should normalise the available information by economic mechanism.
Potential comparison variables include outstanding confirmed obligations, payment-term changes, programme activity, financial statement classification and dependence on funding providers.
The objective is to identify economically comparable exposures rather than impose a uniform debt adjustment on every issuer.
Integrating supplier finance into credit surveillance
A structured research process can monitor programme disclosures at each reporting date.
The analyst first records the programme's key terms and accounting presentation.
Subsequent filings can then be assessed for changes in outstanding balances, activity, payment terms and liquidity discussion.
Material changes can trigger targeted research questions.
For example:
- Has the programme expanded more rapidly than underlying purchases?
- Has management changed its explanation for the arrangement?
- Does the business increasingly depend on extended settlement periods?
- Would a reduction in programme capacity materially alter near-term liquidity?
The findings can then feed into credit models, downside scenarios and investment committee discussions.
This is a more disciplined approach than treating supplier finance either as an automatic accounting concern or as an immaterial financing detail.
How forensic accounting intelligence can support the process
The relevant disclosures may appear in financial statement notes, liquidity discussions, working-capital commentary and accounting policy explanations.
Terminology can vary across issuers and reporting periods.
Automated extraction and structured classification can help investment teams identify arrangements, compare changes and locate primary-source evidence.
The analysis still requires professional interpretation.
A reliable system should distinguish disclosed facts, calculated measures, hypothetical adjustments and unresolved questions.
Helmledgers is developing a source-linked forensic accounting intelligence approach intended to support this kind of evidence-based review.
For credit investors, the goal is to make complex contractual and accounting exposures easier to investigate, not to treat every unusual arrangement as evidence of financial distress.
Conclusion
Supplier finance can be a legitimate and commercially useful form of working-capital management.
For credit and distressed investors, however, it deserves attention because conventional debt and cash flow measures may not fully communicate its economic implications.
Changes in programme size, terms, classification and liquidity dependence can affect the assessment of financial flexibility.
The research question is not simply whether a company uses reverse factoring.
It is whether the company's reported financial position adequately reflects the financing arrangements on which its operating liquidity depends.
Explore Helmledgers
Explore evidence-driven forensic accounting intelligence for institutional investment and risk research.
References
- FASB: ASU 2022-04, Disclosure of Supplier Finance Program Obligations
- IFRS Foundation: Supplier Finance Arrangements amendments
- SEC: MD&A requirements and liquidity disclosures
The financial examples are hypothetical. Supplier finance classification, debt-like adjustments and liquidity implications require transaction-specific assessment. This article is intended for institutional research and does not constitute investment advice.